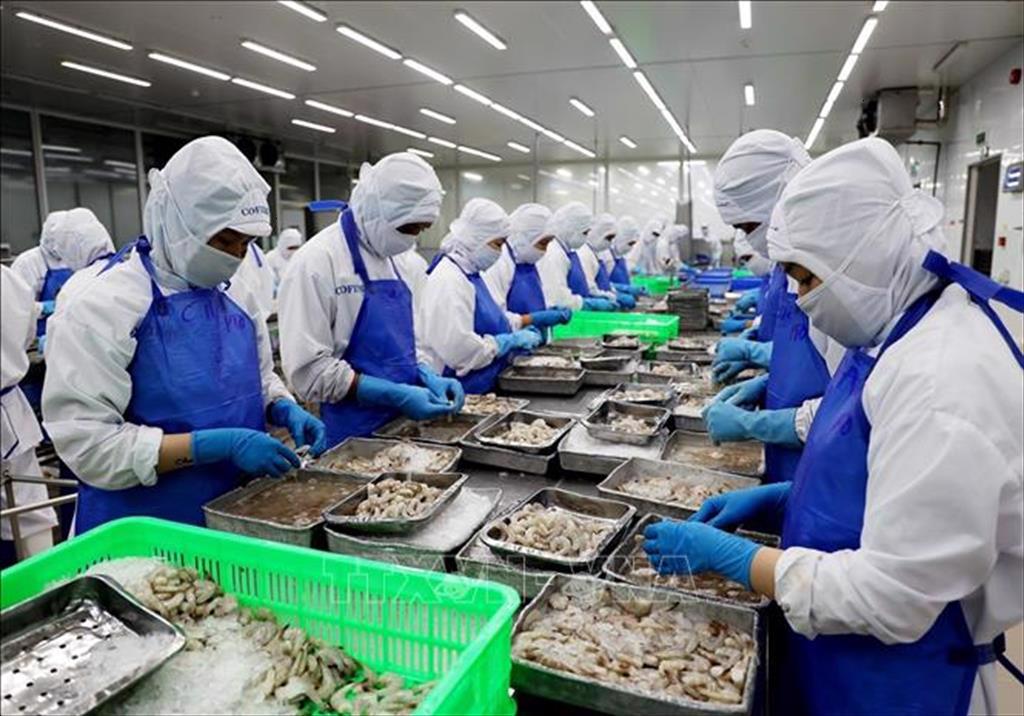
A review of 2024 reveals that seafood stocks rose by 10.3%, underperforming the VN-Index's 12.1% increase.
Despite encouraging growth in consumption volume, most listed companies reported flat or declining growth in net profit after tax attributable to parent company shareholders (NPATMI) during the first three quarters of 2024 (VHC -5%, Fimex VN (FMC) -2%, ANV 0.3%) due to shrinking profit margins, lower or stagnant average selling prices, and higher shipping costs.
Pangasius exporters outperformed shrimp exporters, with VHC increasing by 26% and ANV by 33%, while Minh Phu Seafood Corporation (MPC) decreased by 9% and FMC increased by 11%.
Looking ahead to the seafood sector's prospects in 2025, SSI Research anticipates stable growth in pangasius consumption volume, despite potential risks related to tariffs due to consumer spending tightening.
In the first ten months of 2024, pangasius import volume into the US surpassed its closest substitute, Chinese tilapia, for the first time, according to the National Oceanic and Atmospheric Administration (NOAA). This trend is expected to continue in 2025 as tilapia is projected to face higher tariffs.
In the base-case scenario, Vietnam is expected to face lower tariffs than China. However, for shrimp, additional tariffs would negatively impact consumption volume, as the average selling price of Vietnamese shrimp is already 15-20% higher than that of India and Ecuador. Therefore, the expectation is to maintain stable and competitive average selling prices to mitigate the potential impact of further tariffs.
Highlighting the impact of trade policy, SSI Research indicates that Vietnam's seafood sector is among the most sensitive to potential tariffs imposed by the US, given that shrimp and pangasius exports to the US account for nearly 20% of total export value.
The assumed tariff levels for Vietnam (10-20%) are projected to be lower than those imposed on China. During the previous cycle when tilapia faced a 20% tariff compared to 0% for pangasius, demand for pangasius surged. While tariffs have a less favorable impact on the shrimp sector, FMC has recently expanded its production capacity to focus more on value-added products for the Japanese market.
SSI Research maintains a relatively positive outlook on the sector, anticipating that consumption volume will continue to drive growth. This is further supported by temporary export orders from wholesalers in anticipation of new tariffs. The USD exchange rate is expected to remain strong, benefiting most exporters through exchange rate gains (VHC and FMC), with the exception of companies with substantial USD-denominated loans, such as ANV.
In 2025, companies are projected to achieve revenue growth of 10-16%, with VHC expected to grow by 14.2%, FMC by 16.4%, and ANV by 13%, primarily driven by consumption volume.
Pangasius consumption volume to the US is expected to stabilize, largely due to more competitive pricing compared to Chinese tilapia. VHC’s consumption volume is projected to increase by 10%.
ANV's revenue is expected to face continued headwinds in the Chinese market due to slow consumption recovery. Meanwhile, export volume to the US has not improved since the company received anti-dumping duty exemption two years prior. US revenue continues to represent less than 5% of ANV's total revenue. For FMC, capacity expansion is projected to drive growth, as the company is expected to focus on developing the Japanese market.
Regarding profitability, SSI forecasts a 28% year-on-year increase in post-tax profit attributable to the parent company of VHC, driven by a gradual improvement in average selling prices from USD 3.15/kg in 2024 to USD 3.30/kg (+5%) in 2025. ANV's post-tax profit attributable to the parent company is projected to rebound by 104%, supported by the recovery of the Chinese market from the previous year's low base and accounting for 20% of revenue, in conjunction with other markets (70% of revenue).
FMC’s after-tax profit attributable to the parent company is expected to reach 15%, based on the assumption of flat gross profit margin and selling, general, and administrative (SG&A) expenses as a percentage of revenue, reflecting expectations that shipping costs will remain elevated and anti-subsidy duties will be recognized from Q3 2024.
In terms of valuation, the seafood sector is currently trading at a 2025 price-to-earnings (P/E) ratio of 11x, higher than the historical average P/E of 9x but lower than the peak of 15x observed when the average Pangasius selling price reached USD 5.00/kg, which is 30% higher than the current price. The sector’s valuation and stock prices exhibit a strong correlation with fluctuations in the average selling price. Given the expectation that the average selling price will not increase significantly in the coming year, SSI applies a target P/E of approximately 10-11x to 2025 earnings per share (EPS) to derive target prices.
(vasep.com.vn) Vietnam’s tuna exports sustained their upward trajectory in August 2026, though the pace remained modest at just 2%. The month saw divergent trends across key markets: the US maintained its leading position, Japan and Canada improved, Russia surged and the EU continued to experience a steep downturn. These developments suggest that exporters are entering the final months of the year amid a market environment marked by greater uncertainty.
(vasep.com.vn) Vietnam’s shrimp exports reached $3.3 billion in the first eight months of 2026, up 12% year on year. However, growth momentum is moderating and market divergece is becoming more pronounced, while the US and EU continue to present significant challenges. The latest insights from the Global shrimp forum 2026 (GSF 2026), held in early September, also indicate that the final months of the year will remain highly competitive as global supply continues to expand and buyers place greater emphasis on quality, product specifications, supply consistency and the ability to meet market-specific demand.
(vasep.com.vn) Vietnam’s pangasius exports continued to grow in August 2026, bringing total export value in the first eight months of the year to US$1.5 billion, up 10% year-on-year. August exports alone reached US$205 million, up 6%. However, market performance has become increasingly divergent, with China and Brazil posting positive growth while the U.S. continued to record a sharp decline.
(vasep.com.vn) Vietnam’s seafood exports reached US$1.14 billion in August 2026, up 6.4% year on year, bringing the total for the first eight months to more than US$8.0 billion, an increase of 11.9%. Monthly export value remained above US$1 billion, but August growth was only around half the rate recorded cumulatively through the first eight months. This indicates that the eight-month result was supported significantly by stronger performance in earlier months, while market conditions are entering a less predictable period.
(seafood.vasep.com.vn) Pangasius is attracting growing interest from Japanese seafood companies as prices of many traditional whitefish species remain high and supply becomes increasingly volatile. Notably, seafood group Kyokuyo has recently continued to feature pangasius among its priority products, highlighting its competitive pricing and stable supply.
(seafood.vasep.com.vn) As Vietnam’s tilapia industry searches for new growth opportunities, venturing into brackish-water aquaculture could unlock a formidable competitive moat. Bypassing the volume-and-price bloodbath against established global heavyweights, Vietnam could differentiate itself through high-quality tilapia products tailored to specific farming conditions and value-added market segments.
(seafood.vasep.com.vn) 2026 is rapidly shaping up to be a formidable stress test for Vietnamese pangasius exports to the United States. While exports to alternative markets maintain a resilient growth trajectory, the U.S market has declined significantly. In the first eight months of the year, pangasius exports to the U.S fell by nearly 14% year-on-year, with August alone recording a decline of more than 50%. The trend shows that difficulties in the U.S. market are not driven solely by weak consumer demand, but also by multiple layers of trade barriers that are intensifying simultaneously, particularly additional import tariffs, anti-dumping duties and growing protectionism for the domestic catfish industry.
(vasep.com.vn) Vietnam’s pangasius exports to Japan are showing positive signals in 2026, indicating that the market is opening up greater opportunities for pangasius products, particularly processed and value-added products. In the first seven months of 2026, Vietnam’s pangasius exports to Japan reached US$31 million, up 20% year-on-year. In July alone, export value reached approximately US$5 million, up 30%.
On July 22, 2026, the Government issued Decree No. 292/2026/ND-CP detailing certain articles and providing measures for the organization and implementation of the Law on Foreign Trade Management. The Decree takes effect on September 5, 2026, replacing Decree No. 69/2018/ND-CP.
(vasep.com.vn) Vietnamese pangasius producer Vinh Hoan has won the top prize at the 2026 Seafood Excellence Asia Awards for its Cured Panga Croquette, highlighting the growing potential of value-added pangasius products in international markets.
VASEP - HIỆP HỘI CHẾ BIẾN VÀ XUẤT KHẨU THỦY SẢN VIỆT NAM
Chịu trách nhiệm: Ông Nguyễn Hoài Nam - Phó Tổng thư ký Hiệp hội
Đơn vị vận hành trang tin điện tử: Trung tâm VASEP.PRO
Trưởng Ban Biên tập: Bà Phùng Thị Kim Thu
Giấy phép hoạt động Trang thông tin điện tử tổng hợp số 138/GP-TTĐT, ngày 01/10/2013 của Bộ Thông tin và Truyền thông
Tel: (+84 24) 3.7715055 – (ext.203); email: kimthu@vasep.com.vn
Trụ sở: Số 7 đường Nguyễn Quý Cảnh, Phường An Phú, Quận 2, Tp.Hồ Chí Minh
Tel: (+84) 28.628.10430 - Fax: (+84) 28.628.10437 - Email: vasephcm@vasep.com.vn
VPĐD: số 10, Nguyễn Công Hoan, Ngọc Khánh, Ba Đình, Hà Nội
Tel: (+84 24) 3.7715055 - Fax: (+84 24) 37715084 - Email: vasephn@vasep.com.vn