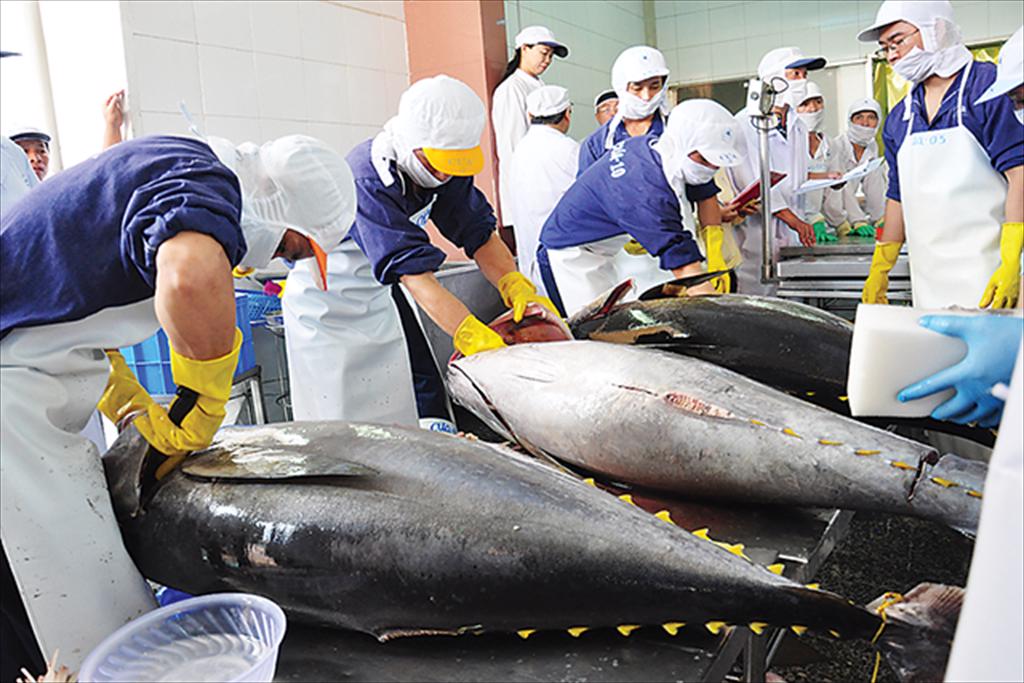
According to the UK Committee on Toxicity of Chemicals in Food, Consumer Products, and the Environment (COT), the average seafood consumption per capita in the UK is approximately 217 grams per person per week. Among this, fatty fish (excluding canned tuna) accounts for about one-quarter, equating to over 50 grams per person per week. Notably, changes in consumer behavior following the COVID-19 pandemic have led to increased demand for processed and canned food products due to their convenience.
In 2024, tuna ranked as the third highest-selling seafood in UK retail markets, following salmon and cod. In the UK, tuna is primarily consumed in quick meals such as sandwiches and travel-friendly meals. According to data from Seafish, tuna accounts for 69% of all canned seafood choices among British consumers. Moreover, given the versatility of fatty fish in various culinary applications, other processed tuna products - such as salads, tuna-based sauces, and sandwiches - are also highly favored. Similar to other European markets, UK consumers are increasingly focused not only on the origin and quality of seafood but also on labor standards, environmental impact, and the sustainability of supply chains. Additionally, fundamental factors such as pricing, processing methods, meal compatibility, and usage settings remain key considerations.
In the tuna sector, the largest suppliers to the UK currently include Ecuador (accounting for approximately 29% of total imports), Mauritius (over 13%), Seychelles (11%), Ghana (10%), and Spain (nearly 6%). Meanwhile, several Southeast Asian suppliers hold smaller market shares but still rank among the top 15 tuna exporters to the UK, including the Philippines (7%), Indonesia (2%), Thailand (6%), and Vietnam (1.4%).
Vietnam Customs data shows that Vietnam’s tuna exports to the UK have maintained continuous growth since the implementation of the CPTPP. Export value increased from $5.1 million in 2021 to nearly $7.9 million in 2024, marking a 54% rise. Entering 2025, the UK remains one of the few markets where Vietnam’s tuna exports continue to grow, with a 24% increase year-on-year.
The CPTPP and UKVFTA agreements have created substantial growth momentum for bilateral trade while opening new development opportunities for Vietnam’s tuna industry, particularly as key export markets face declines due to geopolitical tensions and global economic challenges.
A key change in tariff regulations under the CPTPP is the gradual reduction of tariffs on Vietnam’s processed and canned tuna exports to the UK from 20% to 0% over seven years. Meanwhile, under the UKVFTA, these products currently benefit from a 0% tariff only within a quota of 11,500 tons. In the long run, leveraging tariff preferences from these agreements will provide a competitive advantage for Vietnamese tuna exports in the UK market.
According to industry experts, both the CPTPP and UKVFTA are next-generation free trade agreements that require exporting countries and enterprises to enhance their internal capacities. The most significant advantage of the CPTPP is its rules of origin, which allow greater flexibility for exporters. Following the UK's accession, five other economies have formally applied to join the CPTPP: China, Taiwan (September 2021), Ecuador (January 2022), Costa Rica (August 2022), and Uruguay (December 2022). Among them, Ecuador and China are formidable competitors to Vietnam’s tuna industry. Therefore, Vietnamese enterprises must act swiftly to seize the early mover advantage and capture market share. Additionally, securing a stable domestic tuna supply will be a decisive factor in enhancing Vietnam’s competitiveness in this market.
However, to achieve this, the tuna industry requires further incentives to accelerate growth. Specifically, for fishermen, it is crucial to ensure that, alongside compliance with legal regulations - including IUU fishing rules - they are motivated to expand offshore fishing operations and reinvest in their fleets. Moreover, fishermen must be able to harvest and sell raw materials under normal market conditions. As for businesses, efforts should continue to improve the business environment and simplify administrative procedures.
|
TOP 15 TUNA SUPPLIERS TO THE UK, 2023 - 2024 (Unit: USD thousand, Source: ITC) |
|||
|
Exporters |
2023 |
2024 |
Change (%) |
|
Total |
501.117 |
581.112 |
16 |
|
Ecuador |
144.258 |
168.409 |
17 |
|
Mauritius |
76.037 |
75.286 |
-1 |
|
Seychelles |
55.497 |
64.687 |
17 |
|
Ghana |
50.743 |
55.343 |
9 |
|
Philippines |
26.333 |
40.505 |
54 |
|
Thailand |
18.492 |
34.062 |
84 |
|
Spain |
29.95 |
33.43 |
12 |
|
Peru |
21.719 |
30.925 |
42 |
|
Maldives |
22.581 |
21.337 |
-6 |
|
Korea |
12.866 |
13.805 |
7 |
|
Indonesia |
11.661 |
12.922 |
11 |
|
Portugal |
6.287 |
9.981 |
59 |
|
Vietnam |
6.316 |
8.056 |
28 |
|
Japan |
1.574 |
2.273 |
44 |
(vasep.com.vn) Vietnam’s pangasius export value reached US$1.7 billion in the first nine months of 2026, up 11% year on year. In September alone, exports totaled US$210 million, an increase of 16%. China, the United States, and Brazil were the three largest markets, accounting for 49% of total export value. While China and Brazil maintained their growth momentum, exports to the US remained below the level recorded in the same period last year.
(vasep.com.vn) On November 11, 2026, in Can Tho, the Vietnam Association of Seafood Exporters and Producers (VASEP) will organize the Vietnam Seafood Summit 2026 (VSS 2026) under the theme “Seafood Market Outlook 2027–2029: Opportunities and Headroom for Double-Digit Export Growth.”
(seafood.vasep.com.vn) Business leader Do Ngoc Tai, General Director of Tai Kim Anh Seafood Processing Joint Stock Company, was honored by the Vietnam Chamber of Commerce and Industry (VCCI) with the title “Outstanding Vietnamese Entrepreneur – Thanh Giong Cup 2026” at a ceremony celebrating Vietnam Entrepreneurs’ Day (October 13). The event took place on the evening of October 11, 2026, at the National Convention Center in Hanoi.
(vasep.com.vn) The global tilapia market is becoming increasingly segmented, not only among producing countries but also by product type and destination market. Supply is divided into groups with distinct competitive advantages: large volumes of whole fish and frozen fillets from Asia, high-value fresh fillets from Latin America, and substantial domestic consumption in several major producing countries.
(vasep.com.vn) Vietnam’s tuna exports to the UK grew in the first eight months of 2026, despite signs of slowing import demand in the market. However, sharp fluctuations in orders, competition from major suppliers, and new traceability requirements are creating challenges for Vietnamese exporters.
(seafood.vasep.com.vn) Vietnam is stepping up efforts to combat illegal fishing, protect marine ecosystems, expand digital monitoring, and develop science-based management to ensure the sea can support communities and the economy for generations to come.
(seafood.vasep.com.vn) The EU remains a critical market for Vietnamese shrimp; however, purchasing demand and import patterns are undergoing notable changes. According to Vietnam Customs data, as of September 15, 2026, Vietnam’s shrimp exports to the EU reached nearly $374 million, down 5% year-over-year and accounting for 10.7% of the country’s total shrimp export value. Meanwhile, the EU’s stotal shrimp imports through July 2026 contracted by 7% in volume, exhibiting divergent trends across Southern Europe, Northwestern Europe and Eastern Europe. These dynamics necessitate that Vietnamese enterprises closely monitor individualized market demand, rather than approaching the EU as a monolithic consumer block.
(seafood.vasep.com.vn) In the first eight months of 2026, Vietnam’s exports of surimi and fish cakes remained relatively stable year-over-year compared to 2025. Following a contraction in the initial months, export performance demonstrated improvement from June onward, peaking in August. However, the recovery has been uneven, characterized by divergent trends across major markets: robust growth was recorded in China, Japan, Malaysia, the United States, and Taiwan, whereas export volumes to South Korea, Indonesia, and select European markets contracted.
(seafood.vasep.com.vn) Pangasius remains one of Dong Thap’s key aquaculture species, with the province focusing on developing an integrated value chain covering seed production, commercial farming, deep processing and by-product utilization. The province is promoting high-tech, circular pangasius farming models featuring reduced water exchange and enhanced biosecurity, aiming to improve production efficiency and strengthen control over raw material quality.
(vasep.com.vn) Vietnam’s seafood exports in September 2026 are estimated at US$1.135 billion, up 11.9% year-on-year, bringing total exports in the first nine months of the year to US$9.103 billion, up 11.4%. Behind this double-digit growth, however, increasingly divergent market trends are emerging: China–Hong Kong and ASEAN posted strong growth, while the U.S., EU and Japan all recorded declines in September.
VASEP - HIỆP HỘI CHẾ BIẾN VÀ XUẤT KHẨU THỦY SẢN VIỆT NAM
Chịu trách nhiệm: Ông Nguyễn Hoài Nam - Phó Tổng thư ký Hiệp hội
Đơn vị vận hành trang tin điện tử: Trung tâm VASEP.PRO
Trưởng Ban Biên tập: Bà Phùng Thị Kim Thu
Giấy phép hoạt động Trang thông tin điện tử tổng hợp số 138/GP-TTĐT, ngày 01/10/2013 của Bộ Thông tin và Truyền thông
Tel: (+84 24) 3.7715055 – (ext.203); email: kimthu@vasep.com.vn
Trụ sở: Số 7 đường Nguyễn Quý Cảnh, Phường An Phú, Quận 2, Tp.Hồ Chí Minh
Tel: (+84) 28.628.10430 - Fax: (+84) 28.628.10437 - Email: vasephcm@vasep.com.vn
VPĐD: số 10, Nguyễn Công Hoan, Ngọc Khánh, Ba Đình, Hà Nội
Tel: (+84 24) 3.7715055 - Fax: (+84 24) 37715084 - Email: vasephn@vasep.com.vn