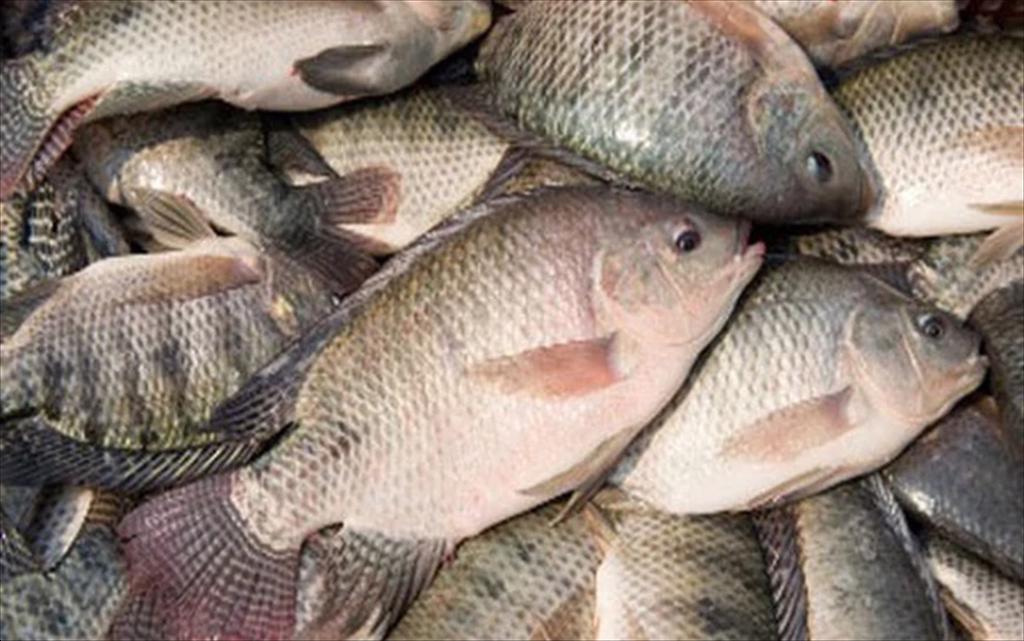
According to the INFOFISH Tilapia 2025 report, China remains the world’s leading tilapia producer. In Asia, Indonesia ranks second, followed by Bangladesh and Vietnam.
Three Supply Groups with Different Product Advantages
The first group comprises China, Vietnam, Indonesia, and Taiwan, which have the capacity to supply large volumes of frozen tilapia. These countries compete directly in the whole-fish and frozen-fillet segments, serving markets that prioritize competitively priced products.
China remains the most prominent supplier in the frozen segment. In the first quarter of 2026, its exports of frozen whole tilapia rose sharply, particularly to Côte d’Ivoire, while shipments to the United States declined significantly. This suggests that China may be redirecting its exports toward other markets, especially Africa, rather than reducing its supply capacity.
Meanwhile, Brazil, Colombia, Mexico, Honduras, and Costa Rica are strong in the fresh-fillet segment. Their geographic proximity to the United States gives them an advantage in meeting requirements for short transit times and product freshness.
The remaining group includes Egypt, Bangladesh, the Philippines, and Thailand. Although these countries have substantial production volumes, a large share is consumed domestically, meaning that not all their output enters international trade in significant quantities. In other words, high production does not necessarily translate into strong competitiveness in global markets.
Trade Flows Are Shifting
The most noticeable changes are taking place in the US market. China remains the largest supplier, but its shipments have declined, while Indonesia and Vietnam are beginning to gain market share in the frozen-fillet segment.
The decline in Chinese tilapia supplies to the United States does not mean that demand for tilapia has disappeared. Rather, the supplier mix and product composition are changing. FAO GLOBEFISH also reported that global tilapia trade continued to shift toward more competitively priced frozen products in 2025.
Brazil presents another notable development. Despite being the world’s fourth-largest tilapia producer, Brazil recorded imports exceeding exports for the first time during the first eight months of 2026, as imports of frozen fillets from Vietnam increased sharply. This demonstrates that even countries with well-developed aquaculture industries may turn to external suppliers when imported products meet their needs in terms of price, specifications, or supply capacity.
Opportunities and Challenges for Vietnam
In the frozen-product segment, China and Indonesia are Vietnam’s two direct competitors. In the US fresh-fillet market, Colombia, Honduras, Costa Rica, and Brazil hold a competitive advantage.
Vietnam benefits from the experience and capabilities developed by its pangasius industry. Its value chain, from farming areas and raw-material procurement to processing and exports, is relatively well established. Processing plants that meet stringent US and EU standards, cost-control capabilities, and favorable natural conditions for expanding farming areas are additional strengths.
These advantages are reflected in the country’s export growth. In the first eight months of 2026, Vietnam’s tilapia exports reached US$90 million, up 43% year on year. Brazil accounted for US$44 million, nearly half of the total export value, while shipments to the United States reached US$21 million.
However, the heavy concentration of exports in Brazil also creates risks. Brazil’s domestic aquaculture industry is responding to the rapid increase in imported fillets, citing concerns about price competition and disease. Market diversification is therefore an urgent priority. Vietnam’s competitiveness will depend not only on pricing but also on its ability to deliver value-added processing, consistent quality, traceability, and products targeting higher-value market segments.
Overall, the global tilapia market is not facing an absolute shortage of supply. The key issue is the segmentation of supply by product type, destination market, and logistical advantages. This ongoing realignment is creating new opportunities for Vietnam, while also intensifying direct competition among producing countries.
(seafood.vasep.com.vn) Vietnam’s tuna exports kept growing in October 2026, lifting the 10-month total past $816 million. Behind the positive figures, though, the global market remains uneven: demand is slow to recover and raw material prices are climbing. Exporters now have to hold on to orders while keeping production profitable.
(seafood.vasep.com.vn) Vietnam’s shrimp exports reached $4.21 billion in the first 10 months of 2026, up 8.8% from a year earlier. Sales to China and several CPTPP markets kept the sector growing, but October’s results were weaker. Exports to the U.S. fell sharply again, and tariff pressure, international competition and rising production costs leave exporters with a tough end to the year.
(seafood.vasep.com.vn) Nearly US$1.7 billion is the projected gap in 2029 between the baseline scenario and a scenario in which Vietnam’s seafood exports grow by 10% annually, according to calculations by VASEP to be presented at Vietnam Seafood Summit 2026. This gap raises a key question for the entire industry: Which markets, products and supply chain improvements will generate the additional growth?
(seafood.vasep.com.vn) Although Germany’s tuna imports have declined, Vietnam’s tuna exports to the market continue to show positive signs. Notably, export value recovered strongly in Q3/2026, and German import data also show Vietnamese products strengthening their position amid competition among suppliers.
(seafood.vasep.com.vn) Seafood exports are holding double-digit growth, but the opportunities are not spread evenly across product groups and markets. As businesses draw up their plans for 2027, Vietnam Seafood Summit 2026 (VSS2026) offers a chance to look ahead together: what to sell, where to sell it, and how to prepare for growth in the coming years.
(seafood.vasep.com.vn) With less than two weeks to go, the Vietnam Seafood Summit 2026 (VSS 2026) will officially take place in Can Tho. Under the theme “Seafood Market Outlook 2027–2029 – Opportunities and Potential for Double-Digit Export Growth,” the Summit is organized by VASEP at a time when seafood businesses are facing rapid market shifts, changing buyer demand, trade policy changes and growing competitive pressure all at once.
(seafood.vasep.com.vn) On October 28, 2026, the China Fisheries & Seafood Expo opened in Qingdao, China. The expo takes place over three days from October 28 to 30, 2026. This is a prestigious specialized seafood exhibition organized annually by Sea Fare Exposition Inc.
(vasep.com.vn) In the first nine months of 2026, Vietnam’s tilapia exports to the CPTPP bloc reached $7 million, marking a 51% year-on-year increase. The bloc rstands as the fourth-largest market for Vietnamese tilapia, trailing Brazil, the US, and Saudi Arabia.
(vasep.com.vn) VASEP has officially announced the program for Vietnam Seafood Summit 2026 (VSS 2026), featuring five in-depth sessions covering industry outlooks, trade barriers, buyer demand, the domestic market, and solutions to improve productivity and reduce costs across the seafood value chain.
(vasep.com.vn) Vietnam’s shrimp exports reached US$3.7 billion in the first nine months of 2026, up 11% year on year. Although growth has been supported by China and several markets within the CPTPP, momentum is slowing as exports to the United States and the European Union decline. Tariff pressures, international competition, and raw material challenges are creating significant hurdles for exporters in the final months of the year.
VASEP - HIỆP HỘI CHẾ BIẾN VÀ XUẤT KHẨU THỦY SẢN VIỆT NAM
Chịu trách nhiệm: Ông Nguyễn Hoài Nam - Phó Tổng thư ký Hiệp hội
Đơn vị vận hành trang tin điện tử: Trung tâm VASEP.PRO
Trưởng Ban Biên tập: Bà Phùng Thị Kim Thu
Giấy phép hoạt động Trang thông tin điện tử tổng hợp số 138/GP-TTĐT, ngày 01/10/2013 của Bộ Thông tin và Truyền thông
Tel: (+84 24) 3.7715055 – (ext.203); email: kimthu@vasep.com.vn
Trụ sở: Số 7 đường Nguyễn Quý Cảnh, Phường An Phú, Quận 2, Tp.Hồ Chí Minh
Tel: (+84) 28.628.10430 - Fax: (+84) 28.628.10437 - Email: vasephcm@vasep.com.vn
VPĐD: số 10, Nguyễn Công Hoan, Ngọc Khánh, Ba Đình, Hà Nội
Tel: (+84 24) 3.7715055 - Fax: (+84 24) 37715084 - Email: vasephn@vasep.com.vn