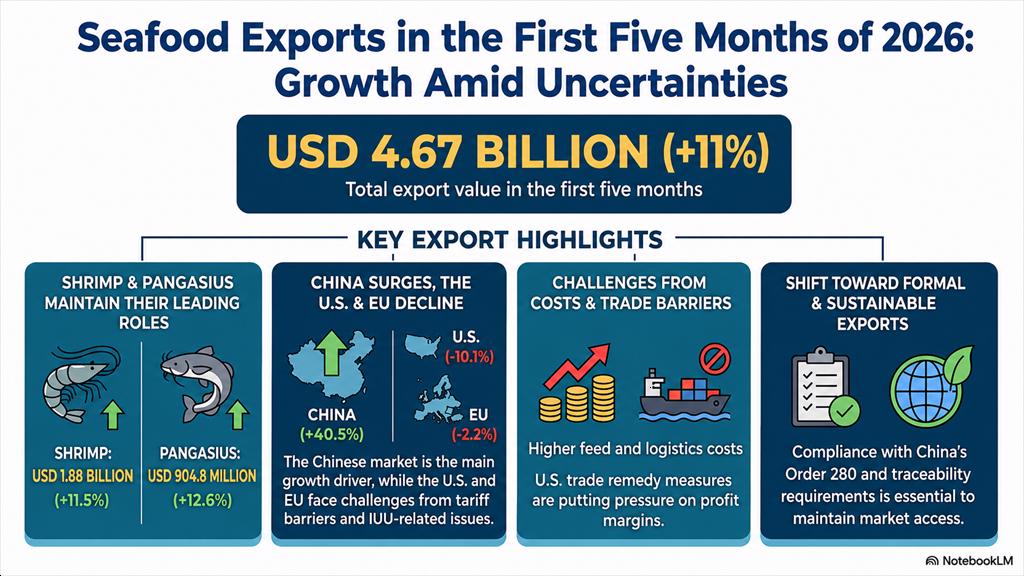
The double-digit growth indicates that the seafood sector has maintained its recovery momentum. However, behind this result lies a less favorable picture: buyers are placing orders more cautiously, market performance is becoming increasingly fragmented, and compliance requirements are emerging as a critical factor for retaining customers.
Shrimp remained Vietnam’s largest seafood export category, generating USD 1.9 billion, up 11.5%, accounting for approximately 40.4% of total seafood export value. Growth during the first five months was driven by recovering demand in several Asian markets, stronger consumption of processed shrimp products, and lobster exports to China. Nevertheless, prospects for the second half of the year will depend not only on current growth figures but also on the industry’s ability to address emerging production and order-related challenges.
One notable issue is the mismatch between domestic production and import demand. In many farming regions, producers are shifting toward larger shrimp sizes to maximize value per unit of production. Meanwhile, several major markets are increasing demand for smaller-sized shrimp that better suit budget-conscious consumers. This mismatch could affect order negotiations, product specifications, and raw material procurement plans. In addition, Vietnamese shrimp continues to face significant cost pressures, intense competition from Ecuador, India, and Indonesia, as well as U.S. trade remedy measures, particularly anti-dumping duties, countervailing duties, and administrative reviews.
Pangasius exports reached USD 905 million in the first five months, up 12.6%. This remains one of the most promising product categories thanks to stable supply, competitive pricing, and growth opportunities in China, ASEAN, the Middle East, the EU, and several emerging markets. As consumers in many countries continue to prioritize affordable protein products, pangasius is well positioned to maintain its role within the whitefish segment.
However, production-related pressures are mounting. Fingerling prices have remained high since 2025, while feed, transportation, and other input costs continue to rise, making farmers more cautious about expanding farming areas. If this trend persists, farming costs may increase further, putting pressure on raw material prices and processors’ profit margins. On the market side, China has shown signs of renewed purchasing after a slowdown, although demand is increasingly concentrated on larger-sized fish. Meanwhile, exports to the United States continue to face anti-dumping duties, trade investigations, and stringent requirements related to traceability, quality, and compliance.
A significant opportunity for pangasius comes from developments in the global whitefish supply. Pollock production is expected to decline by around 30%, while rising fuel costs have pushed raw material prices up by 30–50%. Concerns over supply shortages are prompting importers to shift part of their demand toward farmed fish species with more stable supply. Vietnamese pangasius, along with tilapia, could benefit from this trend if producers can maintain raw material availability, ensure farming quality, and preserve their pricing advantage.
In contrast to shrimp and pangasius, tuna exports declined by 6% to USD 372 million. The sector is facing significant challenges from domestic raw material shortages and increasingly stringent traceability requirements. U.S. regulations on marine mammal protection, seafood import monitoring programs, and the EU’s anti-IUU fishing measures are raising compliance costs, extending documentation procedures, and affecting order negotiations.
Other seafood categories posted stronger growth but still face risks. Squid and octopus exports reached USD 304 million, up 18%; crab and other crustaceans generated USD 160 million, up 19%; while bivalve mollusks reached USD 122 million, up 22.8%. These products continue to find opportunities in Japan, South Korea, China, the United States, and the EU, particularly in processed, convenient, and high-value segments. However, heavy dependence on wild-caught and legally imported raw materials remains a key weakness. Rising fuel costs, expensive logistics, and stricter origin certification requirements are directly affecting production volumes, raw material prices, and delivery schedules.
By market, China and Hong Kong remained the strongest growth drivers, with imports of Vietnamese seafood reaching USD 1.2 billion, up 40.5%. Increased demand for shrimp, pangasius, crab, mollusks, and other high-value seafood products has significantly supported export performance. However, China is rapidly transitioning toward formal import channels and imposing stricter controls on product quality, biosecurity, enterprise registration, farming area codes, and traceability. Decree 280, which took effect on June 1, 2026, replacing Decree 248, clearly signals that future growth in China will require greater export standardization.
Conversely, exports to the United States fell 10% to USD 689 million, while exports to the EU declined 2.2% to USD 435.6 million. These markets continue to exert pressure through tariffs, trade remedies, traceability requirements, food safety standards, anti-IUU measures, and sustainability regulations. Meanwhile, Japan posted modest growth of 0.4%, South Korea increased by 4%, and ASEAN expanded by 16.8%, helping Vietnamese exporters diversify market risks.
Based on the results of the first five months, VASEP forecasts that Vietnam’s seafood exports could grow by approximately 8–10% in 2026, exceeding USD 12 billion, provided that demand in China remains strong, pangasius retains its price competitiveness, shrimp improves its competitive position, and seafood exporters resolve challenges related to IUU compliance, raw material certification, and traceability.
On the other hand, if compliance costs, logistics expenses, trade barriers, and raw material shortages persist, export growth in the second half of the year is likely to slow, particularly for shrimp, tuna, squid, octopus, crab, and other wild-caught seafood products.
(seafood.vasep.com.vn) With less than two weeks to go, the Vietnam Seafood Summit 2026 (VSS 2026) will officially take place in Can Tho. Under the theme “Seafood Market Outlook 2027–2029 – Opportunities and Potential for Double-Digit Export Growth,” the Summit is organized by VASEP at a time when seafood businesses are facing rapid market shifts, changing buyer demand, trade policy changes and growing competitive pressure all at once.
(seafood.vasep.com.vn) On October 28, 2026, the China Fisheries & Seafood Expo opened in Qingdao, China. The expo takes place over three days from October 28 to 30, 2026. This is a prestigious specialized seafood exhibition organized annually by Sea Fare Exposition Inc.
(vasep.com.vn) In the first nine months of 2026, Vietnam’s tilapia exports to the CPTPP bloc reached $7 million, marking a 51% year-on-year increase. The bloc rstands as the fourth-largest market for Vietnamese tilapia, trailing Brazil, the US, and Saudi Arabia.
(vasep.com.vn) VASEP has officially announced the program for Vietnam Seafood Summit 2026 (VSS 2026), featuring five in-depth sessions covering industry outlooks, trade barriers, buyer demand, the domestic market, and solutions to improve productivity and reduce costs across the seafood value chain.
(vasep.com.vn) Vietnam’s shrimp exports reached US$3.7 billion in the first nine months of 2026, up 11% year on year. Although growth has been supported by China and several markets within the CPTPP, momentum is slowing as exports to the United States and the European Union decline. Tariff pressures, international competition, and raw material challenges are creating significant hurdles for exporters in the final months of the year.
(vasep.com.vn) Markets are changing faster, buyer requirements are becoming more demanding, and trade barriers are growing increasingly complex. In this environment, seafood businesses need more than an understanding of current market conditions. They need a longer-term perspective to answer a critical question: Where will growth opportunities come from in 2027–2029, and what should businesses do now to prepare? This is one of the key reasons why VASEP is organizing Vietnam Seafood Summit 2026.
(vasep.com.vn) In the first eight months of 2026, Vietnam’s pangasius exports to the Middle East reached US$113 million, up 7% year on year from the same period in 2025. Growth has become more pronounced in recent months. In August alone, exports to the region totaled US$20 million, an increase of 24%. This indicates that demand for Vietnamese pangasius in the Middle East is gradually recovering after a slowdown in March, although the pace of recovery varies across markets.
(vasep.com.vn) China’s shrimp imports continued to grow strongly in 2026, while Vietnam’s shrimp exports to the market also recorded notable growth. However, behind these positive figures lie two distinct trends: Chinese consumption is growing more slowly than imports, and lobster accounts for a substantial share of Vietnam’s shrimp exports to China, making its product mix significantly different from those of Ecuador and India. Exporters therefore need to assess each segment carefully to understand the opportunities and risks.
(vasep.com.vn) Changing markets, shifting buyer demand, and increasingly complex trade barriers are raising a key question for Vietnam’s seafood industry: Where will the new growth opportunities lie in 2027–2029?
(seafood.vasep.com.vn) As of the end of August 2026, Vietnam’s tilapia exports to the United States reached $21 million, representing a steep 48% year-over-year decline and accounting for 23% of the country's total tilapia export turnover. Frozen fillets accounted for 78% with the remainder consisting of whole frozen tilapia and frozen cuts.
VASEP - HIỆP HỘI CHẾ BIẾN VÀ XUẤT KHẨU THỦY SẢN VIỆT NAM
Chịu trách nhiệm: Ông Nguyễn Hoài Nam - Phó Tổng thư ký Hiệp hội
Đơn vị vận hành trang tin điện tử: Trung tâm VASEP.PRO
Trưởng Ban Biên tập: Bà Phùng Thị Kim Thu
Giấy phép hoạt động Trang thông tin điện tử tổng hợp số 138/GP-TTĐT, ngày 01/10/2013 của Bộ Thông tin và Truyền thông
Tel: (+84 24) 3.7715055 – (ext.203); email: kimthu@vasep.com.vn
Trụ sở: Số 7 đường Nguyễn Quý Cảnh, Phường An Phú, Quận 2, Tp.Hồ Chí Minh
Tel: (+84) 28.628.10430 - Fax: (+84) 28.628.10437 - Email: vasephcm@vasep.com.vn
VPĐD: số 10, Nguyễn Công Hoan, Ngọc Khánh, Ba Đình, Hà Nội
Tel: (+84 24) 3.7715055 - Fax: (+84 24) 37715084 - Email: vasephn@vasep.com.vn